Business vehicle insurance cover for small fleets and owner-drivers
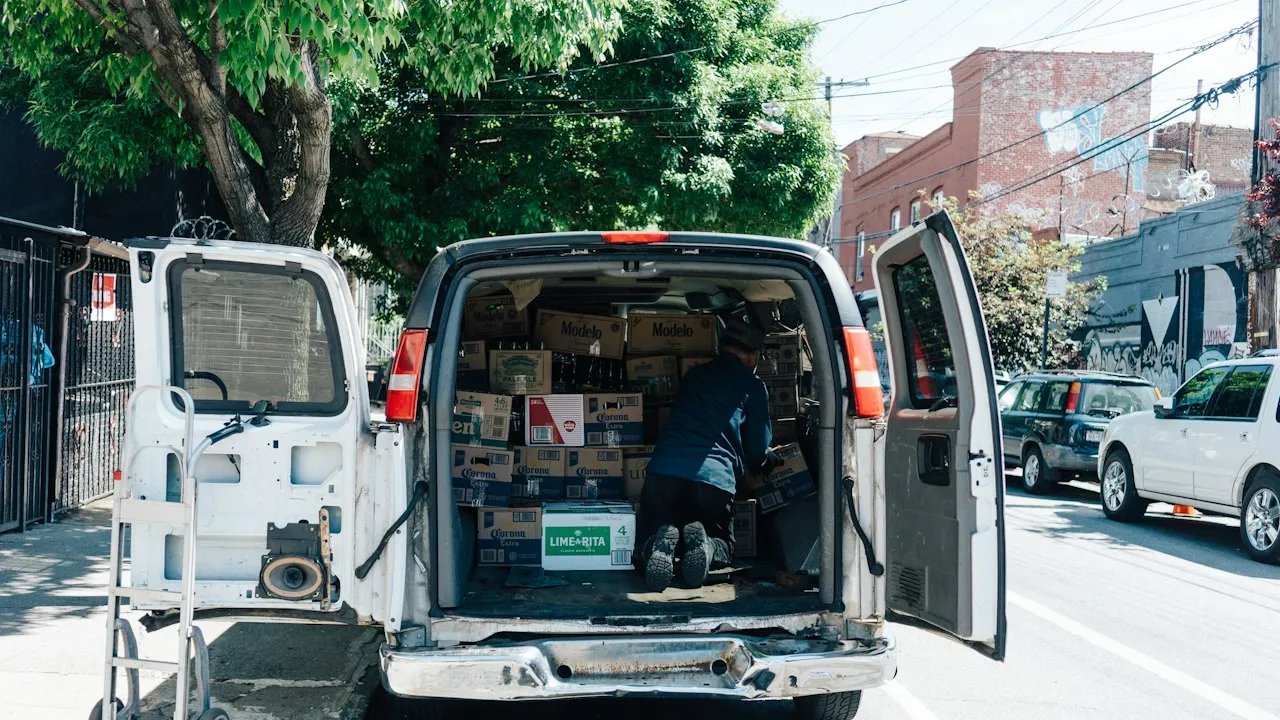
Company vehicles are working assets, but they also create financial exposure every time they leave the depot, visit a customer or carry valuable equipment. For SMEs, tradespeople and owner-drivers, business vehicle insurance should reflect the reality of daily operations rather than a generic private motor policy. The right arrangement can protect vehicles, drivers, third parties and the equipment that keeps the business moving.
Identify how your business uses each vehicle before comparing cover
Private car insurance may allow limited commuting, but it rarely covers the full range of commercial activity. Driving between customer sites, transporting materials, delivering goods, carrying tools or allowing several employees to use a van can all require commercial motor cover. A policy should state the intended business use accurately, since an undeclared activity may lead to a reduced settlement or a declined claim.
Start by listing every vehicle and its role. A self-employed electrician using one van has different needs from a catering company operating three refrigerated vehicles, or a sales business with employees driving company cars across the country. Consider whether vehicles are owned, leased, hired occasionally or used by staff under a “grey fleet” arrangement.
Broader insurance decisions also benefit from a joined-up view of property, liability, vehicles and employee exposure. Businesses seeking guidance on how motor protection fits within wider risk planning can learn more about comparing insurance options and identifying gaps between operational risks and existing policies. This approach can help you avoid treating vehicle cover as an isolated annual purchase. It also supports clearer discussions with brokers or insurers about your company’s actual activities.
Mileage has a direct effect on exposure. A van covering 35,000 miles a year through urban areas faces different accident frequency risks from a vehicle used twice a week for local appointments. Record annual mileage honestly, including personal journeys where they are permitted under the policy.
“Good insurance starts with a clear picture of the risks your business accepts every day.”
Driver profiles can change the premium and the available cover
Insurers consider who drives as closely as they consider what is driven. Age, licence history, driving convictions, claims records and length of driving experience can influence terms. An open-driving policy may feel convenient for a growing team, yet named-driver arrangements can sometimes offer more control and a lower premium.
If temporary workers, apprentices or subcontractors use company vehicles, check the policy wording before handing over the keys. Some policies set a minimum driver age, exclude drivers with certain convictions or restrict cover for drivers who have held a licence for less than a specified period.
Key commercial motor cover options, limits and common exclusions
The foundation of commercial motor insurance is third-party liability cover. This protects against claims for injury or property damage caused to others, subject to the policy limits and terms. However, liability cover alone does not repair your own van after an accident, theft, fire or vandalism.
Comprehensive commercial motor cover usually adds protection for damage to your own vehicle. This may be appropriate where a vehicle is essential to operations, has a high replacement value or is financed through a lease agreement. Third-party, fire and theft cover can offer a middle ground, but it will not generally pay for accidental damage to your vehicle.
When comparing policies, ask practical questions:
- Does the policy provide a replacement vehicle after an insured incident, and for how long?
- Are tools, stock, samples or customer goods carried in the vehicle covered?
- Is windscreen repair included without affecting the main no-claims discount?
- What excess applies to accidental damage, theft and young drivers?
- Are European journeys, overnight parking or trailer use included?
- Does cover extend to hired vehicles while your own vehicle is being repaired?
Tools and goods need particular attention. A standard motor policy may insure the van but exclude contents, or impose a low single-item limit. A plumber carrying specialist testing equipment or a retailer delivering high-value stock may need separate tools-in-transit, goods-in-transit or business contents protection.
Read exclusions as carefully as the headline benefits
Vehicle insurance exclusions are often where costly surprises arise. Common restrictions include theft from an unlocked vehicle, theft of tools left visible overnight, use outside declared business activities, unapproved modifications and driving by an uninsured or unauthorised person. Some policies also limit claims where the vehicle has not been maintained in a roadworthy condition.
Payload and vehicle use deserve close scrutiny. A panel van insured for carrying tools may not automatically be suitable for paid courier work, hazardous materials or heavy goods beyond the permitted weight. Likewise, a personal car used for occasional client visits may need different cover from a car used for food delivery or passenger transport.
Reduce fleet risk without choosing cover on price alone
A low premium may be attractive, especially for a small business managing tight cash flow. Yet the cheapest policy can carry a large excess, narrow driver permissions or limited replacement-vehicle arrangements. The true cost appears when an accident takes a vehicle out of service and the business cannot complete booked work.
Fleet risk management can improve safety and strengthen your position when seeking renewal terms. Keep driving licence checks up to date, document vehicle inspections, maintain service schedules and set clear rules for mobile phone use, loading and overnight parking. Telematics can also help some businesses monitor mileage, harsh braking, speeding and route patterns.
Claims history matters, but it should be reviewed rather than accepted passively. Look at the causes of previous incidents. Reversing collisions may call for parking sensors or driver training, while recurring thefts may justify upgraded locks, secure storage or revised procedures for leaving equipment in vehicles.
A disciplined insurance quote comparison should balance price with operational resilience. Compare like for like, using the same vehicle details, driver information, annual mileage and required business use. Check excesses, indemnity limits, exclusions and claims support before making a decision.
Choose commercial vehicle cover that supports your daily operations
The most suitable policy is the one that matches how your company actually works, from the people behind the wheel to the goods carried in the back. Review cover when you add vehicles, recruit staff, change contracts, expand delivery areas or purchase expensive equipment.
Keep these priorities in view:
- Declare business use, mileage and driver details accurately.
- Match cover to the vehicle’s value and its role in earning revenue.
- Check protection for tools, goods, replacement vehicles and hired vehicles.
- Compare excesses and exclusions, not only annual premiums.
- Use training, maintenance and security measures to reduce avoidable claims.
With a clear understanding of your risks, you can select commercial motor cover that protects both your vehicles and the continuity of your business.